Adjusted gross income (AGI) is your total income for the year minus specific deductions allowed by the IRS, which are known as adjustments to income. Your AGI serves as the starting point for determining your federal tax bracket and how much you’ll owe. And if you live in a state that has an income tax, your AGI will generally also be the starting point for calculating your state taxes.
In other words, the lower your AGI, the lower your overall taxable income will be. It’s also the number the IRS uses to determine if you qualify for certain tax credits and deductions.
Read this blog post to learn how to calculate your AGI, what deductions lower it, and the reason why getting it right matters for business owners specifically.
Why does AGI matter?
AGI matters because it’s your starting point in figuring out how much you owe in taxes. Once you calculate your AGI, you subtract the standard or itemized deduction to get your taxable income, which is the number that actually determines your tax bill.
This number also decides whether you qualify for certain tax credits and deductions, how much of some deductions you’re allowed to claim (medical expenses, for instance, are only deductible above 7.5% of your AGI), and whether you’re eligible to contribute to retirement accounts like a Roth IRA.
In states with income tax, you’ll need your AGI to calculate your state taxable income as well. Some will use state-specific income adjustments modified for their tax code, but you can expect to use your federal AGI as a starting point for determining your state income tax liability and eligibility for certain state deductions and credits.
But taxes aren’t the only place your AGI shows up. If you’ve ever applied for a mortgage, refinanced a loan, or filled out a FAFSA application, you’ve probably had to report it there. Government agencies may consider your AGI to determine whether you qualify for certain benefits or programs, and if you’re applying for a business loan, your lender will ask for it too.
On top of that, business owners have more riding on this number than a typical employee would. Because your income is self-reported and often comes from more than one source, AGI becomes one of the few standardized figures a lender can use to verify your income. It also fluctuates more than a salary does because, unlike an employee, business owners can influence the final amount based on the deductions they take. So, for business owners in particular, a lower AGI may not always be the goal (more on this later).
What counts as an adjustment to income?
Adjustments are specific expenses the Internal Revenue Service (IRS) lets you subtract from your total income before you apply the standard or itemized deduction. You can claim them regardless of the kind of deduction you take later.
They’re often called “above-the-line” deductions, with the line being the AGI itself, which is reported on line 11 of IRS Form 1040. They’re different from itemized deductions and the standard deduction, which are sometimes called “below-the-line” deductions, since they’re claimed after line 11 and reduce your taxable income instead of your AGI.
The IRS updates the list of available adjustments annually, although several appear consistently every year. Here are some of the most common ones you may be able to take when calculating your AGI.
Deductible portion of self-employment taxes
Self-employment tax covers Social Security and Medicare, the same taxes a traditional employee splits with their employer through payroll. Since the IRS treats you as both the employer and the employee when you’re self-employed, you pay both halves yourself. However, you can deduct the employer-equivalent half of what you paid during the year, which helps offset that burden.
Keeping your self-employment tax and contractor payments organized throughout the year makes this deduction much easier to calculate accurately, which allows you to avoid reconstructing this deduction by hand at tax time.
Self-employed health insurance premiums
If you’re self-employed, you may be able to deduct health insurance premiums for you, your spouse, and your dependents. This includes medical, dental, vision, and qualifying long-term care coverage. Note that this deduction is generally limited to your net self-employment income for the year, and it isn’t available if you’re eligible for coverage under a spouse’s employer-sponsored plan.
Contributions to self-employed SEP, SIMPLE, solo 401(k)s, and other qualified plans
If you’re self-employed, you have access to a range of retirement plans created specifically for business owners:
SIMPLE IRA
Solo 401(k) (for business owners with no employees other than a spouse)
If you have employees, other qualified plans like a standard 401(k), profit-sharing plan, or defined benefit plan may be available instead. Contributions you make for yourself, and for any employees if the plan covers them, are generally deductible, though the exact amount depends on your business entity type and the plan you choose.
Setting up and tracking these contributions, especially if you have employees on the plan too, is a lot easier with the right payroll support in place.
Individual retirement account (IRA) contributions
If you contributed to a traditional IRA during the year, you may be able to deduct some or all of your contributions, depending on your MAGI (also known as modified adjusted gross income—we’ll unpack this in a bit).
Whether the deduction phases out at all depends on whether you (or your spouse) are covered by a workplace retirement plan. If neither of you is, the full contribution is generally deductible regardless of income.
Keep in mind that a traditional IRA is different from a Roth IRA, which doesn’t offer an upfront deduction but grows tax-free instead. Only traditional IRA contributions count as an adjustment to your AGI.
Student loan interest
If you paid interest on a qualified student loan during the year, you may be able to deduct up to $2,500 of it, even if you don’t itemize. Your loan servicer typically sends a Form 1098-E showing how much interest you paid, which makes this one easier to track down than some of the other adjustments on this list.
Whether you qualify, and how much of that $2,500 you can actually deduct, depends on your filing status and MAGI. This adjustment phases out gradually rather than cutting off all at once, so make sure to check your MAGI against the current threshold instead of assuming you’ll get the full amount.
Health savings account contributions
If you have a high-deductible health plan, you may be able to subtract contributions to your health savings account (HSA) when calculating your AGI. For 2026, that’s up to $4,400 for individual coverage or $8,750 for family coverage, with an extra $1,000 allowed if you’re 55 years of age or older.
Unlike most tax-advantaged accounts, an HSA lets your funds grow tax-free, and you won’t owe tax on any withdrawals used for qualified medical expenses either. Unused funds also roll over from year to year, so you don’t have to spend what you contribute in a given year.
Penalty on early withdrawal of savings
If you withdrew money from a certificate of deposit or similar account before it matured, you can deduct any penalty the bank or credit union charged you for the early withdrawal.
Your bank or credit union typically reports this penalty on Form 1099-INT, so you just need to carry the number over when you file. This adjustment isn’t tied to your income or filing status, so if you paid the penalty, you generally qualify for the deduction regardless of how much you earn.
Keep in mind that above-the-line deductions aren’t free money. Contributing more to, say, an SEP-IRA to lower your AGI only saves you your tax rate multiplied by your contribution, not the full dollar amount. So if you’re in the 22% tax bracket, a $1,000 adjustment saves you $220 in tax, not $1,000.
This list isn’t comprehensive, and the adjustments you’re entitled to depend on your specific situation. So for further information, consider reaching out to a tax professional to help you identify any others you might be missing.
AGI vs. taxable income: What’s the difference?
These two terms are very similar, but refer to two different numbers used at different points in your tax calculation.
Adjusted gross income refers to your total income after above-the-line deductions. This figure helps determine your eligibility for certain tax credits or deductions.
Taxable income is your AGI after subtracting either the standard deduction or your itemized deductions. This number is what the IRS uses to calculate your income tax liability and tax bracket.
For a full side-by-side comparison of AGI, MAGI, taxable income, and gross income, take a look at the table further down in this blog post.
How do I calculate my AGI?
The basic formula for calculating AGI is simple:
Total income - adjustments to income = AGI
Here’s a step-by-step breakdown to help you calculate yours, whether your income comes from a W-2, a business you run, or both.
Add up your gross income for the year
Start by taking your total income from all sources. If your income only comes from a W-2 salary—say, as a full-time employee, for example—this part is mostly done for you. Your payroll provider already tracks your wages, so that number flows straight into your tax return.
But as a business owner, determining your gross income for the year gets a little more complicated.
Gross income refers to all of the income you received over the year from all sources, including monetary gifts, property, tips, interest, dividends, and rent. (Hint: look at lines 1-8 on Form 1040.) And if you’re self-employed or run a business, this means you’ll likely need to pull figures from several different sources yourself, including:
Schedule C net profit
1099 income from clients or side hustles
W-2 wages
Owner’s draws (which aren’t a paycheck and don’t get taxed the same way a salary does)
K-1 income (your share of profit if your business is a partnership or S corporation)
Rental income
Capital gains
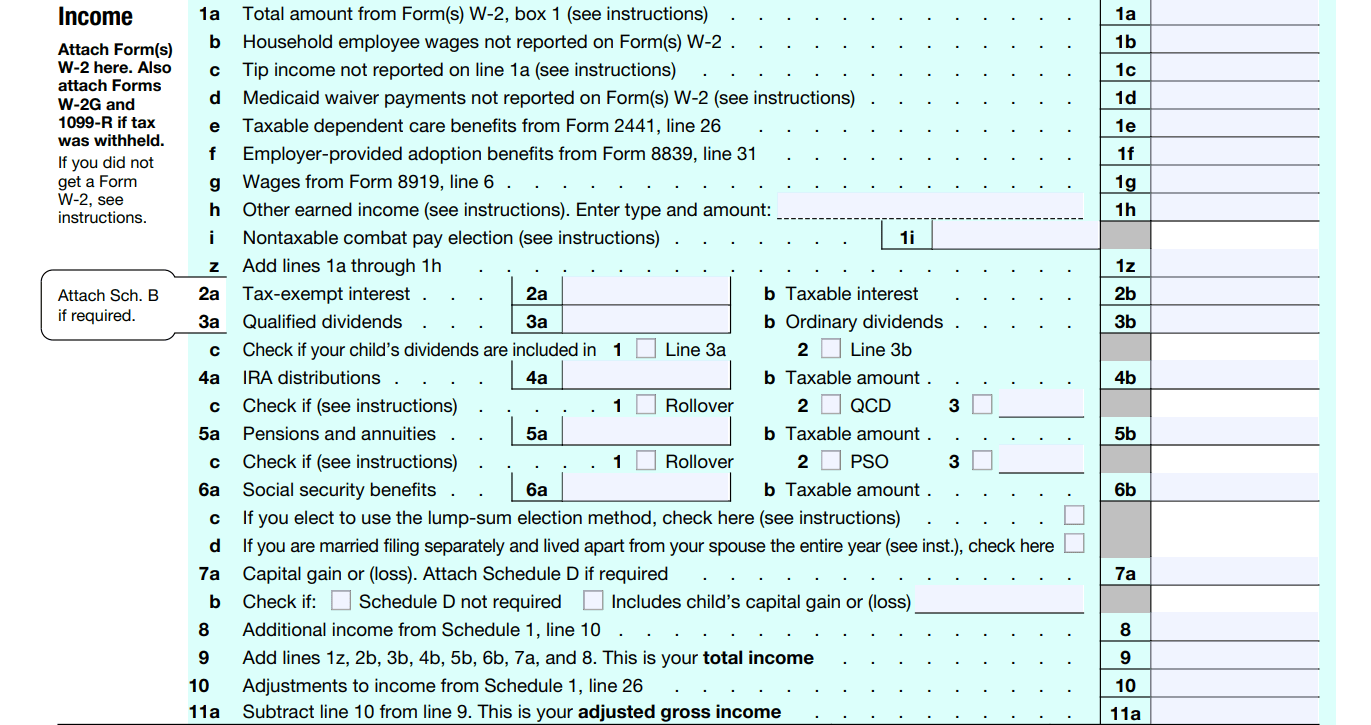
Don’t include things like tax-exempt interest, qualified Roth IRA distributions, or the nontaxable portion of your Social Security benefits. Unlike adjustments to income, these should never enter your AGI calculation. For more on what does and doesn’t count toward your gross income, check IRS Publication 525.
Because your income is typically scattered across bank statements, invoices, and a handful of different platforms (at minimum), this is the step where business owners often get stuck—and that’s not even taking into account the possibility of inconsistent bookkeeping.
If you pay yourself as an employee through payroll, whether just for yourself or alongside a team, your wage records are already gathered in one place. Many payroll platforms generate year-end reports and W-2s automatically, so your total wages for the year are available at a moment’s notice.
Calculate your adjustments
Next, go through the adjustments and add up the ones that apply to you.
Note that a few of these, like the traditional IRA deduction and student loan interest deduction, phase out based on your MAGI (which we’ll get to in a bit). Review the credits and deductions table further down in this article to confirm your eligibility before assuming you get the full amount.
Consider working with an accountant or tax professional to make sure you’re calculating these accurately, especially if your situation is more complex.
Subtract your adjustments from your gross income
Subtract your adjustments from your gross income, and you have your AGI. This becomes the starting point for calculating your taxable income and checking your eligibility for certain tax credits and deductions, which we covered earlier in this post.
Where to find your AGI on Form 1040
Your AGI appears on Line 11 of Form 1040 (or 1040-SR or 1040-NR), near the end of the income section, on your most recently filed income tax return.
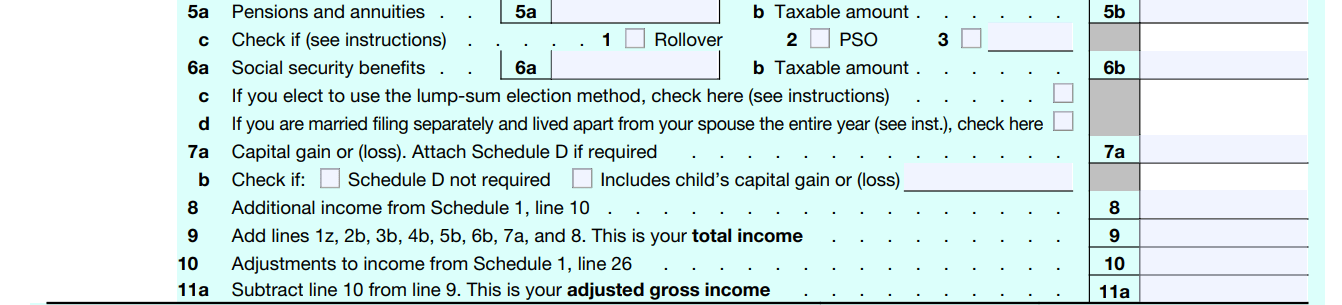
If you’re e-filing your return yourself, you’ll often need this number. The IRS uses this (or your Self-Select PIN from your prior year’s tax filing) to verify your identity.
If you don’t have a copy of last year’s return on hand, you can pull your AGI using the IRS’s Get Transcript tool instead.
What is MAGI, and when do you actually need it?
Modified adjusted gross income is your AGI with certain adjustments added back in. It doesn’t directly change your taxable income. Instead, it determines whether you’re eligible to take some of the adjustments used to calculate your AGI in the first place, which can in turn affect your taxable income and your overall tax bill.
You don’t need to calculate MAGI for every adjustment. It mostly comes up when you’re claiming something with an income limit attached, such as:
Student loan interest payments
Tuition and fees
IRA contributions
Foreign earned income
Income earned on US savings bonds
If your income is comfortably under these thresholds, you likely don’t need to worry about MAGI at all. But when you’re close to one, it’ll be especially helpful to run the numbers and see where you land.
Keep in mind that the IRS can change the list of adjustments year over year, and each tax benefit calculates MAGI a little differently. So whenever you’re asked to provide MAGI, follow the specific instructions on how to calculate it for that benefit to ensure you provide an accurate figure.
AGI vs. MAGI
AGI and MAGI are very similar, but with one key difference. AGI refers to your total income minus your adjustments to income. MAGI is your AGI with certain deductions added back in to determine your eligibility for certain tax benefits and retirement plans. As a result, your MAGI will always be larger than or equal to your AGI.
While this section focuses on AGI and MAGI specifically, it may be helpful to see them alongside a few other tax terms you’ve come across in this article. Here’s a table that breaks them down to help you better understand what each one is and when it’s used:
Term | What it is | Where it shows up |
Gross income | All income before any deductions | Starting point for your tax return |
AGI | Gross income minus adjustments | Form 1040, line 11 |
MAGI | AGI plus certain adjustments added back | Used to check eligibility for specific deductions and credits |
Taxable income | AGI minus standard or itemized deduction | What your tax bill is based on |
How AGI affects your eligibility for tax credits and deductions
Many tax credits and deductions phase out as your AGI (or MAGI) increases, which means the same credit can be worth its full amount to one business owner and nothing to another, all depending on their income.
Some credits and deductions have a hard cutoff—once your AGI crosses the set threshold, you lose eligibility entirely. Others phase out gradually, so the dollar amount you can claim shrinks a little at a time as your income increases, rather than disappearing all at once.
Either way, the number you land on after adjustments gets measured against these thresholds to determine whether you’re eligible for the tax benefit. Aside from determining your tax liability, this is another reason why it’s important to get your adjustment calculations correct.
Because everything gets measured as one combined figure, the IRS doesn’t care about where your income comes from when calculating AGI. W-2 wages, Schedule C profit, and investment income all count the same toward the total figure. A strong year for your business can push you past a threshold for a sought-after tax credit while you were unaware, even if nothing else about your finances changes.
Some examples of tax credits and deductions that commonly affect business owners include:
Credit or deduction | Filing status | AGI or MAGI threshold |
Child Tax Credit | Single, head of household, married filing separately | Phases out starting at $200,000 AGI, reduced $50 per every $1,000 over the threshold |
Child Tax Credit | Married filing jointly | Phases out starting at $400,000 AGI, reduced $50 per every $1,000 over the threshold |
Traditional IRA deduction (filer covered by a workplace plan) | Single, head of household | Phases out between $81,000 and $91,000 MAGI |
Traditional IRA deduction (filer covered by a workplace plan) | Married filing jointly | Phases out between $129,000 and $149,000 MAGI |
Traditional IRA deduction (filer not covered, spouse is) | Married filing jointly | Phases out between $242,000 and $252,000 MAGI |
Student loan interest deduction | Single, head of household | Phases out between $85,000 and $100,000 MAGI |
Student loan interest deduction | Married filing jointly | Phases out between $175,000 and $205,000 MAGI |
Premium tax credit (ACA marketplace coverage) | All filing statuses | No fixed dollar threshold, based on household income as a percentage of the federal poverty line |
Several of these credits and deductions phase out gradually over a range rather than being cut off at a single number, so falling within the range usually results in a partial benefit rather than none. Note that, if you’re married filing separately, the student loan interest deduction isn’t available at any income level, regardless of how much interest you paid.
How does AGI affect Medicare premium calculations (IRMAA)?
If you’re on Medicare (or getting close to it), AGI also determines how much you pay for Medicare Part B and Part D premiums, through what’s called IRMAA (Income-Related Monthly Adjustment Amount).
IRMAA is based on your MAGI from two years ago, not your current income. So, for example, your 2026 Medicare premiums are based on your 2024 tax return. If you had an unusually high-income year two years ago, whether from a strong year in the business, a one-time asset sale, or a large retirement account withdrawal, you may see the effect on your premiums well after the fact—and with little warning.
The standard Medicare Part B premium applies below a set MAGI threshold. Part D doesn’t have a single standard premium since it varies by plan, but the same IRMAA threshold applies to it too. Above that threshold, Medicare uses a tiered system of five brackets, each one adding a surcharge on top of your existing premium, whether that’s the standard Part B amount or whatever you’re already paying for your Part D plan. Depending on the bracket, that surcharge can add hundreds or even thousands of dollars in additional costs for both.
If you’re a business owner planning for retirement, your AGI calculations become especially important. Because of the two-year lookback, a decision you make today (like the timing of a business sale or a large distribution) can affect your Medicare costs two years down the road.
For more information specific to your tax situation, get in touch with a tax pro or financial advisor—especially if you’re within a few years of Medicare eligibility and expect a high-income year.
Does it matter how you pay yourself?
It does, because the way you pay yourself affects how much control you have over your AGI. If you pay yourself a salary through payroll, a lot of your AGI-related decisions are already decided for you. Pre-tax deductions like a 401(k) contribution or an HSA payroll deduction reduce your W-2 wages before they ever hit your tax return, so the adjustment happens automatically with little for you to manage manually.
But if you’re self-employed and report income on Schedule C, you have more moving pieces and more decisions to make—for instance, deciding how much to contribute toward retirement or whether certain expenses qualify. There’s more potential benefit, but also more room for error if the records aren’t organized well.
Neither option is better than the other. It just means that the question of “How do I lower my AGI?” has a different answer depending on your sources of income.
Can business owners have a different AGI calculation than employees?
Yes, because total income is typically calculated differently for each one. Business owners also often have adjustments available that don’t apply to a typical employee.
However, the basic AGI formula doesn’t change, and that calculation still applies to everyone. Instead, what changes is how much work goes into calculating your AGI and how many adjustments are available to you when you do.
Let’s take a look at some of the nuances of AGI that affect business owners (and self-employed individuals) in particular.
The income sources are different
An employee’s total income usually starts with a single number from their W-2 wages.
A business owner’s total income can come from several places, including net profit from Schedule C if you’re self-employed, K-1 income if you’re part of a partnership or S corp, plus any wages if you pay yourself a salary. All of it gets added together before adjustments come into play, so business owners often have more pieces to gather and more room for mistakes before they can even calculate their total income.
This also means that taxes usually aren’t withheld automatically the way they are from a paycheck. An employer withholds taxes from an employee’s wages throughout the year, but income from self-employment or a business generally isn’t withheld unless you set that up yourself. That’s why many business owners need to pay estimated taxes quarterly, based on their expected AGI for the year, rather than settling everything up at once when they file during tax season.
Some adjustments only apply to business owners
A few of the adjustments discussed earlier in this article are only available to self-employed people, including:
Deducting half of your self-employment tax
Deducting self-employed health insurance premiums
Contributing to a SEP-IRA, SIMPLE IRA, or solo 401(k)
An employee doesn’t have access to these adjustments. Their retirement and health insurance contributions typically happen through payroll instead. And because these contributions are made pre-tax, they reduce an employee’s W-2 wages directly rather than appearing as a separate adjustment on their return.
Losses can work differently too
If a business has a bad year, a net loss on Schedule C can reduce total income, and in some cases, reduce AGI below zero.
An employee’s W-2 wages don’t work this way. A paycheck doesn’t go negative, so this kind of downside exposure is specific to business owners and self-employed people.
However, it comes with a tradeoff. A loss like this generally can’t be carried back to reduce a prior year’s taxes, but it can usually be carried forward indefinitely to offset taxable income in future years.
S corporation income is taxed differently
If you own an S corporation and pay yourself a reasonable salary through payroll, that salary gets taxed like any other W-2 employee’s wages. But if you also receive additional profit distributions from the business, those are taxed differently, aren’t subject to self-employment tax, and are handled separately from your salary when it comes to total income.
This is a commonly misunderstood area for small business owners, since it means that part of your income looks like an employee’s and the other part doesn’t. Because distributions aren’t subject to self-employment tax, some S corp owners may be tempted to minimize their salary and maximize their distributions.
But the IRS requires you to be paid a reasonable salary for the work you do. If it’s set too low in comparison to your distributions, the IRS can reclassify some of that distribution income as wages, along with back taxes and penalties. So if you own an S corporation, consider working with a tax professional to determine an appropriate salary for your role in the business.
AGI calculation examples for business owners
Example 1: Self-employed freelancer
Say you’re a single filer running a freelance business, and you made $120,000 in net Schedule C profit for the year. Here’s how your adjustments might work out:
Half of self-employment tax: about $8,478
Self-employed health insurance premiums: $9,600
HSA contribution: $4,300
Traditional IRA contribution: $6,000
Total adjustments: $28,378
Total income - adjustments to income = AGI
$120,000 - $28,378 = $91,622 AGI
Now say you also paid student loan interest during the year. Because your AGI is already close to the phase-out range for that deduction, you’d need to check your MAGI against the current-year threshold before assuming you get the full deduction.
Example 2: S corp owner with a salary and distribution
Now say you run your business as an S corporation instead. Again, you made $120,000 this year, but this time split between a reasonable salary through payroll and a profit distribution:
W-2 salary (via payroll): $80,000
Profit distribution from the business: $40,000
Total income: $120,000 (the same as the freelancer example from above)
You also make the same HSA and IRA contributions as you did in the freelancer example above:
HSA contribution: $4,300
Traditional IRA contribution: $6,000
Total adjustments: $10,300
Total income - adjustments to income = AGI
$120,000 - $10,300 = $109,700 AGI
Since the profit distribution isn’t subject to self-employment tax in this example, there’s no self-employment tax deduction to claim. In both examples, you have the same total income and the same HSA and IRA contributions, but a $17,922 difference in AGI ($109,700 vs. $91,622), entirely because of which adjustments are available under each business structure.
(Note that this simplified example doesn’t model the S corporation health insurance premium rules, which work differently than they do for a Schedule C filer and require the premiums to run through payroll to qualify for a deduction.)
As we can see from these two examples, how you structure your business changes which tax benefits you have access to, even when the income itself looks identical on paper.
Should you try to lower your AGI?
Most people might try to focus on lowering their AGI to reduce their taxable income and, therefore, lower their overall tax liability.
But for business owners, your approach might look different.
A lower AGI can help you qualify for credits, deductions, and retirement accounts that phase out at higher incomes. But AGI also shows up in situations where a lower number can work against you—like a mortgage application, an apartment lease, or a business loan—where a lender or landlord is trying to verify how much you make. An AGI that’s too low can make it look like you earn less than you actually do, which can hurt your chances of qualifying.
Instead, consider working to lower your AGI when it’s tied to something specific you’re trying to qualify for, rather than making it an automatic goal every year. If you’re not sure whether a particular adjustment will help or hurt your overall financial situation and goals, talk to a tax professional before you make the contribution.
5 strategies to reduce AGI
If you’ve decided that lowering your AGI serves a specific goal, such as keeping more of your income out of a higher tax bracket, here are some ways to do so legally. Keep in mind that not every strategy below will apply equally, as the amount of control you have depends on how you pay yourself.
Some of these strategies focus on claiming eligible above-the-line deductions, but remember that most of these aren't "free" reductions. They typically shift money into a different account, defer income to a later year, or reduce what's available to you now.
Contribute to a health savings account if you’re on a high-deductible health plan
If you’re on a high-deductible health plan, contributing to an HSA (which we talked about earlier in this blog post) is a straightforward way to lower your AGI. If you haven’t reached the current-year contribution limit yet, it could be valuable to do so before the year ends.
Contribute to a qualified retirement account
If you’re on payroll and want to reduce your AGI, consider contributing as much as you can to a 401(k) or similar plan. If you’re self-employed, a SEP-IRA, SIMPLE IRA, or solo 401(k) lets you set aside a large portion of your income tax-free, since eligible contributions reduce your AGI now while also saving for the future.
Each plan type has its own annual contribution limit. For 2026, that’s:
Up to $72,000 for a SEP-IRA (or 25% of compensation, whichever is less)
Up to $72,000 for a solo 401(k) ($80,000 if you’re 50 or older)
Up to $17,000 for a SIMPLE IRA
You can also contribute to a traditional IRA. For 2026, the limit is $7,500 ($8,600 if you’re 50 or older), and contributions may reduce your AGI by the same amount you contribute. Whether your contribution is deductible depends on your MAGI and workplace plan coverage, as we covered earlier in this article.
Deduct self-employed health insurance premiums
Newer business owners often overlook this option, but it’s a great strategy to take advantage of if you qualify. To claim it, you’ll need to calculate your deduction using Form 7206 and report it on Schedule 1.
If you own an S corporation, however, this works a bit differently. The premiums need to run through payroll and get added to your W-2 wages first before you can claim the deduction on your personal return.
Since this deduction depends on your net self-employment income, you may want to revisit your estimate partway through the year if your income changes significantly, rather than assuming your full premium will be deductible when you file.
Time your income when you have flexibility
If you’re self-employed and use cash-basis accounting, you may have some control over when you invoice or collect payments near the end of the year. For example, if you’d normally send a December invoice, waiting until January to do so instead pushes that income onto next year’s tax return.
Note that this only helps if you have a specific reason to shift it, like staying under a tax benefit threshold this year. The income also doesn’t disappear either—it just moves to next year instead. So this strategy works best with a clear goal in mind, rather than doing so automatically year after year.
Harvest capital losses
If you have additional investments outside of retirement accounts, selling ones that have lost value can offset gains elsewhere in your portfolio and lower your total income for the year. Unlike the other strategies on this list, this one reduces your total income directly rather than working as an above-the-line adjustment.
If your losses exceed your gains, you can typically deduct up to $3,000 against other income, with any excess carried forward to future years.
Let Gusto handle the recordkeeping for you
To get to your AGI, you’ll need an accurate picture of what you actually earned during the year. And for many business owners, that’s the part that takes up the most time and effort.
If you’re self-employed or work with contractors, tracking down 1099 income and payments can get complicated fast, especially if that income comes from more than one client or platform.
Keeping contractor payments and 1099 forms organized throughout the year ensures you’re not completely reconstructing your total income every time you need to calculate your AGI.
But if you run payroll for yourself and any employees, you don’t need to start from scratch every time. Gusto automatically generates and files your W-2s at year-end, so your wage totals are ready to go whenever you need them, whether that’s for your own return or for a lender asking about your income. And if you also offer HSA or retirement benefits, the platform handles those too, managing retirement plan administration and syncing HSA contributions automatically.
If pulling your AGI together has you digging through spreadsheets and old pay stubs, Gusto’s payroll and benefits tools can help make the process easier for you next year. Create your free account today.
AGI Frequently Asked Questions
Is AGI the same as net income?
No. “Net income” usually refers to business profit, or what’s left after subtracting business expenses from revenue. That net income (for example, your Schedule C profit) becomes part of your total income. AGI is a separate calculation done later, once that total income is added up. So your net income feeds into AGI, but the two numbers aren’t interchangeable.
Does AGI include Social Security income?
Only the taxable portion, not the full amount you receive. Depending on your filing status and other income, 0% to 85% of your Social Security benefits can be taxable, and whatever portion is taxable gets included in your AGI.
How does a self-employed person calculate AGI differently?
Self-employed filers start with net business income, such as Schedule C profit or a share of partnership or S corporation income, rather than W-2 wages. They also have access to adjustments that an employee doesn’t, like the self-employment tax deduction, self-employed health insurance premiums, and retirement plan contributions.
What is a good AGI and does the IRS set thresholds?
There is no such thing as a universally “good” AGI. That said, the IRS does set income thresholds tied to AGI (or MAGI) that determine whether you qualify for specific tax benefits or retirement plans. So, whether a given AGI is “good” really depends on what you’re trying to qualify for.
Can AGI be negative?
Yes. This can happen if your adjustments and business losses exceed your other income, for example, if you’re a business owner with a net operating loss and few other income sources. A negative AGI isn’t an error, though it does affect things like whether certain credits apply and how a loss might carry forward to future tax years.